


Building long-term wealth with robo-advisors in Germany

Robo-advisors have now become a common commodity in Germany. Trading ETFs is a solid fundation to any retirement plan. Robo-advisors automate that part of your financial planning.
I am now a father of two three, with a steady income, generating enough cash to spare and think about the future. I’ve been a robo-advisor user for several years. They are a part of my long-term financial goals.
In this guide, you will read the outcome of my research, my current portfolio progress & what to consider regarding taxes & providers.

Feel free to skip the general introduction on robo-advisors to read the Germany-related providers here. Happy to answer your questions in the comments’ section too.

What are robo-advisors?
A robo advisor a technology-heavy alternative to trade stocks and commodities yourself in Germany, or to hire a financial advisor to do that for you, all of that at costs usually contained below 1%.
An algorithm is managing your portfolio of assets, automating as much as possible, in order to cut costs.
Robo advisors in Germany are offering to do that by diversifying the portfolio you will automatically acquire over time. This is done mostly through ETFs (Exchange Traded fund), a package of stock and bonds. Based on your risk profile, it will also do a risk re-balancing for you, in case your portfolio deviates from your target.
ETFs also participate to reduce costs because it’s cheaper to trade than commodities or bonds at 0,30% in most cases.
In my particular case, thinking about robo advisors in Germany is simply a consequence of my retirement planning strategy. I don’t want to beat the market, i don’t want to engage in short-term equity or stock trading. I want to simply match the average market performance, with as little costs as possible, with a set and forget approach. It’s all about distributing risks. That is exactly what robo-advisors can do for me.
Very famously, the legendary Warren Buffet said that “not beating the market” was the best approach for the average investor. So someone like me, someone like you too.

To be clear, i will not rely exclusively on ETFs to reach my long term goals but i think they are solid foundation. I also plan to have real estate into the mix and maybe some more traditional products
Who are robo-advisors for? In which case is it relevant?
Robo advisors are made for people who are comfortable trusting an algorithm, who wants a low-commitment option with a reasonable return for the risk involved. There is also often not minium investment sum to begin with. In a nutshell, it’s great for the following people:
- Beginners who want to start investing but feel overwhelmed by the complexity of the financial markets.
- Busy people who prefer an automated service to handle their investments while they focus on other things.
- Long-term investors who are looking for a low-cost, hands-off way to grow their wealth over time.
A robo-advisor is relevant when you:
- Want a low-cost, automated solution for investing in diversified portfolios without needing to pick individual stocks or funds.
- Don’t have the expertise to build and manage an investment portfolio on your own.
- Prefer a set-it-and-forget-it approach to investing, where the platform handles rebalancing and managing risk for you.
- Are looking for easy access to investment opportunities, especially in ETFs (exchange-traded funds), with low minimum deposit requirements.
It’s quick to set up because most robo advisors in Germany will ask you a few questions to define your profile, based on age, family situation, income target and use of the money invested.
A robo-advisor is not relevant when you:
- you like to do day-trading on the market, trying to be ahead of the curve.
- you are looking to speak to a real human, for advice on wealth management in general.
- you are able to trade ETFs yourself and able to rebalance it once it a while, then probably don’t sign up for one.
- you would like to learn more about trading, as every decision is automated, taken off your hands so to say.
The main robo-advisors in Germany
The following table lists and compares the top 7 robo-advisors in Germany for private investors, consisently recommended online and on r/eupersonalfinance.
| Provider | Min. starting capital | Risk profile | Managed? | Fees |
|---|---|---|---|---|
| Quirion | €0 | Tailored portfolios to match your risk-return profile | Passive | 0.48% – 1.20%, first €10,000 invested are free of management fees for one year |
| growney | €500 | can be based on conventional or sustainable investments | Passive | 0.38% – 0.68% |
| Scalable Capital | €1,000 | Determined by the investor | Passive | 0.49% – 0.75% |
| Whitebox | €25 | Determined by the investor | Hybrid | 0.35% – 0.95% |
| Gerd Kommer Capital | €25 | Determined by the investor | Passive | 0.60% – 0.70% |
| Weltsparen ETF Robo | €500 | Determined by the investor | Passive | 0.33% service fee plus 0.15% ETF costs for a total of 0.48% |
| eToro | $10 | Determined by the investor – no algorithm to suggest the best Smart Portfolio | Passive | No annual management fees but other fees apply |
Robo advisors are fairly new animals in the land of Goethe, so it has taken time for them to do well in the tests conducted by heavy weights like the Handelsblatt and the almighty Stiftung Warentest.
Here is a summary of sentiments from the sources regarding the top 7 robo advisors in Germany for private investors, along with 2-3 pros and cons for each provider:
Quirion
- Overall impression: Sources consistently rank Quirion as one of the best, if not the best, robo advisors available in Germany.
- Pros:
- Excellent overall concept with a wide range of investment options.
- Offers three different service packages to suit individual investor needs.
- No minimum investment required.
- Cons:
- Fees can vary depending on the chosen pricing model and can be over 1% in some cases.
growney
- Overall impression: Growney is consistently praised for its simplicity and ease of use. Best for beginners and “set-and-forget” types of people.
- Pros:
- User-friendly platform that makes investing simple.
- Offers both classic and sustainable investment strategies.
- Low fees, starting at 0.68% per annum.
- Cons:
- Requires a minimum investment of €500.
Scalable Capital
- Overall impression: Scalable Capital is viewed as a reputable and well-established platform. For non-German speaker, this is a rare provider can do it all in English.
- Pros:
- Offers pre-built portfolios tailored to individual goals and preferences.
- Wide range of investment strategies, including options for climate, value, or megatrends.
- Offers a junior depot for children.
- Offers service in English.
- Cons:
- Requires a minimum investment of €1,000.
Whitebox
- Overall impression: Whitebox is recognized for its hybrid investment strategies and portfolio customization options.
- Pros:
- Combines automated portfolio management with both active and passive investment approaches.
- Offers a high degree of portfolio customization.
- Low minimum investment of €25.
- Cons:
- Fees can be relatively high, ranging from 0.35% to 0.95%.
Gerd Kommer Capital
- Overall impression: Positive. Gerd Kommer Capital benefits from the strong reputation of its founder and offers a well-regarded investment strategy.
- Pros:
- Based on the well-known and respected Kommersche Weltportfolio investment strategy.
- Offers a low minimum investment of €25.
- Cons:
- Portfolio composition is not disclosed prior to registration.
Weltsparen ETF Robo
- Overall impression: Positive. Weltsparen is considered a strong overall performer with good conditions and transparent investment concepts.
- Pros:
- Winner of the rolling 1-year performance (including costs).
- Very low fees, consisting of a 0.33% service fee plus 0.15% ETF costs for a total of 0.48%.
- Offers “pockets” for implementing savings goals.
- Cons:
- Each investor can only create one portfolio, limiting the pursuit of multiple savings goals.
eToro
- Overall impression: Positive. eToro is a popular choice for its smart portfolios and social investing features.
- Pros:
- Offers “Smart Portfolios” that provide diversified exposure to major market trends without incurring portfolio management fees.
- Well-known platform for social investing.
- English all the way
- Cons:
- Investors must choose their own Smart Portfolio as there is no algorithm to provide recommendations.
- Other fees may apply besides annual management fees.
- Requires a minimum investment of $500.
Robo advisors & German taxes
A few thins to keep in mind:
- For expats living in Germany, it’s important to know that residency makes you liable for tax on worldwide investment income.
- In Germany, profits from selling ETFs and dividends are subject to capital gains tax taxed (“Abgeltungsteuer“) of 25%, plus a 5.5% solidarity surcharge and, if applicable, 8-9% church tax. This leads to an effective rate of roughly 26.4% to 28%.
- Each taxpayer receives an annual tax-free allowance (the Sparer-Pauschbetrag), which is €1,000 for singles and €2,000 for married couples; gains or dividends up to that amount are exempt from tax.
- Tax applies when you sell ETF shares and realize a profit. If you hold accumulating ETFs that reinvest earnings instead of distributing them, an annual notional “advance lump sum” (Vorabpauschale as defined by InvStG § 18.) is also taxed to reflect unrealized gains. When the ETF is eventually sold, any previously taxed advance lump sums are deducted to avoid double taxation.
- Using a German broker is easier, they will declare everything to the Finanzamt for you.
This simulator lets your calculate what you will owe at the end of the year if you take the money out.
Robo advisors in Germany for retirement
Should you stick with traditional pension products like Riester-Rente or bAV, or opt for modern, flexible solutions like ETFs via robo advisor? Each option has its pros and cons, from stability and tax benefits to flexibility and potential returns.
| Feature | ETFs | Riester-Rente | Rürup-Rente | Direct Insurance (bAV) |
|---|---|---|---|---|
| Risk | High (market-dependent) | Low | Medium | Low |
| Returns | Potentially high | Low to medium | Medium | Low |
| Flexibility | High | Low | Low | Low |
| Tax Benefits | No | Yes | Yes | Yes |
| Fees | Low | High | High | Medium |
| Government/Employer Support | No | Yes | No | Yes |
| Liquidity | High (accessible anytime) | Locked until retirement | Locked until retirement | Locked until retirement |
Maybe a mix of both traditional & robo advisors products is the winning ticket? That’s where financial advisor can enter into play.
A word of warning
Like for all investments, money is not guaranteed at the end of the day. The forecasts they give are only forecasts. But remember; time on the market beats time to market; we are here on the long-haul, through ups and downs.
Time in the market beats timing the market
A common say about ETFs traders.
If there is a hard hit and your robo advisor goes bankrupt, make sure that your money is insured/backed by another bank. And of course then, there are costs.
My experience with robo advisors in Germany so far
After looking at the different options, I decided to open an account with Growney, essentially because of its low fees, interface & barrier to entry.
I have been fairly happy with the experience so far:
- Signing up was easy but required some back & forth for ID verification. There was a little hick-up on the way. Since Growney is trading american commodities, I had to fill-in some anti-money form for the American authorities (pretty weird).
- Onboarding & picking the risk profile was well done. It never felt forced but rather a well-meaning guidance.
- Interface is clear & modern.
- I regularly get nudges via email with tips to educate myself as an investor.
- Customer service is responsive & helpful.
- It automatically generated the right documents for the tax declaration with the Finanzamt.
- Con: they don’t have an English interface.
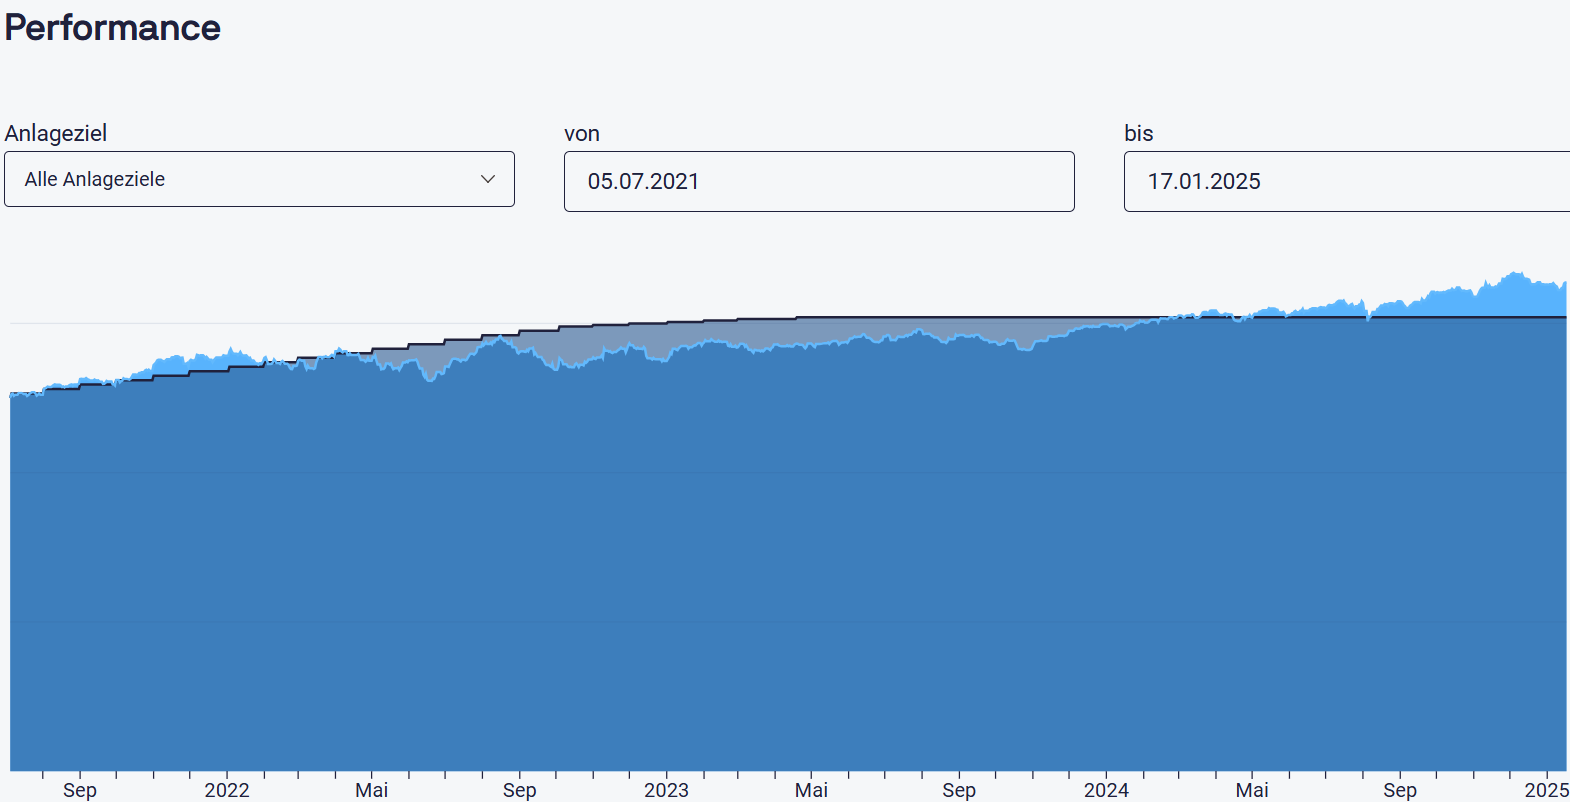
This is my performance so far (7,66% overall, 2,19%/year). With the current economic conditions, I’m not too worried as it follows market trends. It was doing fine until oil, inflation & food prices started to increase a lot in early 2022. And of course, the invasion of Ukraine has had an effect. 2024, things started to look brigther again.
Please note that this page is work in progress and that it doesn’t constitute financial advice. If you plan to put money away, talk to a licensed professional.
Robo advisors with ETFs in Germany – sources and references
- „Diese Versicherungsbeiträge können Sie von der Steuer absetzen.“ Die Versicherer. Accessed MM DD, YYYY. https://www.dieversicherer.de/versicherer/altersvorsorge/news/diese-versicherungsbeitraege-koennen-sie-von-der-steuer-absetzen-141800.
- Riedl, Dominique. “ETF und Steuern: alle Steueraspekte im Überblick.” justETF, February 26 2025. https://www.justetf.com/de/academy/etf-und-steuern.html.
- justETF. “Vorabpauschale ETF Rechner – Der ETF Steuerrechner.” Accessed MM DD, YYYY. https://www.justetf.com/de/etf-steuerrechner.html.
- Keller, Levin. “ETF sparen mit Rürup-Hülle: Mehr Rendite für den Preis der Freiheit.” Medium, March 20 2018. https://medium.com/@levino/etf-sparen-mit-r%C3%BCrup-h%C3%BClle-81d739ff644a.
- micobo GmbH. “Develoments of the Robo Advisory Market in Germany 2018.” Medium, January 15 2019. https://micobo.medium.com/develoments-of-the-robo-advisory-market-in-germany-2018-3821cf240da1.
- “Robo-advisor.” Wikipedia. Last modified Nov, 2025. https://en.wikipedia.org/wiki/Robo-advisor.
- “Robo-Advisor: Digitale Anlagehelfer im Test & Vergleich.” Finanztip, July 12 2024. https://www.finanztip.de/robo-advisor/.
Thanks a lot for the article. At this stage, it seems Growney would be the best option for me (a combination of low taxes plus the app itself) but it seems they don’t offer service in English and I wouldn’t feel 100% comfortable operating in only German). How important do you think this is? Also the taxes topic, is this done directly by the robo-advisor itself as far as I understood, right?
Also, I have another more general question. I have been investing with a financial advisor since a couple of years ago, using the Deutsche Bank service but the fees are really high (around 5%). I am making a monthly investment, but would you recommend stopping it and leaving the funds running until there is enough profit? Would you instead take the money out on the funds that are showing a positive result and move to a robo-advisor with lower fees?
Thanks Bastien for the article. My question is about taxes, do you pay taxes on your return every year or only when you withdraw money from the investement account? Thanks!
Hi,
First of all, many thanks for taking the time to put this information for free.
Do you have any recommendations for financial advisors in Berlin that speak a bit of English? Also, for someone who wants to put around 500 euros per month for retirement, would you recommend robo advisors or having a financial advisor?
Thanks
Hi,
Nice I found your post. I am a foreigner in Germany with poor German knowledge and I am looking for investing information in English.
I want to start investing (long term) and a roboadvisor looks a good option.
Do you have experience with any of them?
They all don’t seem to have an English interface.
How do you handle the taxes? is it different if you use ETFs? if you reinvest the profit do you pay taxes (long term investment)?
thanks!